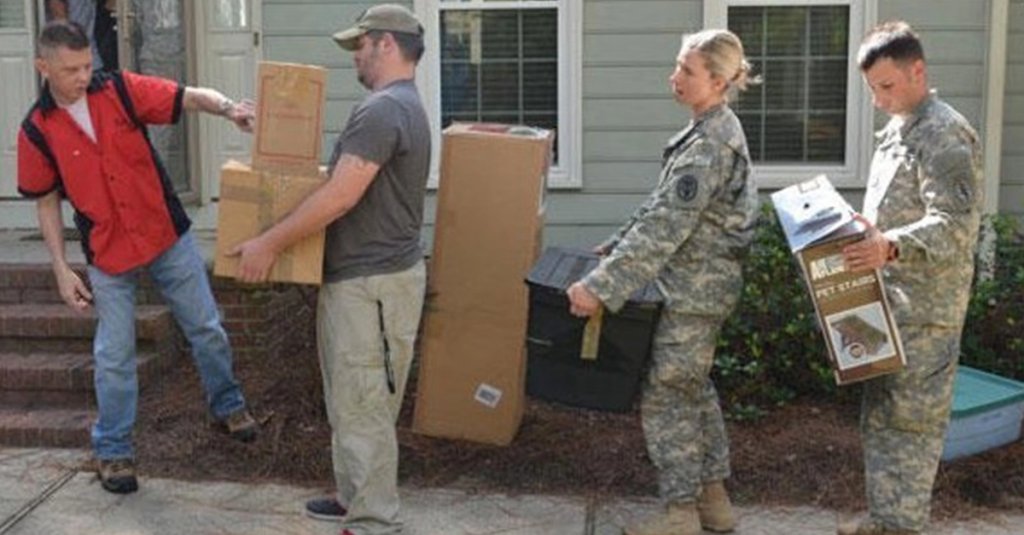
Moving every two to three years is one of the most stressful experiences for military families. Having worked with thousands of military and veteran families, we’ve identified the critical maneuvers that can turn a chaotic relocation into a strategic win.
Also Read: Someone wrote a list of 65 ways civilians can simulate military life and it’s hilarious
Whether you’re active duty or a veteran settling down, here is your tactical guide to navigating the PCS housing market.
Give Yourself a Long Runway
PCS orders don’t care about market timing, so you have to create your own advantage. Ninety to 120 days out, set a realistic housing budget, check your credit, and assemble your “war chest” of documents. These include your latest LES, W-2s, bank statements, and your VA Certificate of Eligibility (COE).
Having these ready is the difference between a smooth takeoff and a grounded mission.
To Buy or Rent?
For PCS success, decide quickly, but use data to inform your decision. If you expect to be in place for less than three years, renting is almost always the right choice, once you factor in costs, maintenance, and the risk of a flat resale market. The three-to-five-year range is the “gray zone” where local market conditions and your appetite for being a landlord start to matter more.
Buying builds equity and stability, but it ties you to market swings and potential vacancy if you depart early. If you do buy and must move, you could keep the existing home as a rental property and longer-term investment. Renting maximizes your flexibility when orders or jobs shift.
It is vital to stress-test your decision for PCS success: ask yourself what happens if you have to move sooner, or stay longer, than you had expected.
Follow the Math
Don’t just look at the sticker price. Compare your all-in monthly housing cost, including Principal, Interest, Taxes, and Insurance (PITI); HOA fees; utilities; and the cost of your commute, against your Basic Allowance for Housing (BAH) or take-home pay, and against monthly rent.
Keep in mind, homeownership is also a lifestyle choice. If you enjoy spending your weekends maintaining and improving your property, and having more space and flexibility, then owning might be a great investment. If you’d prefer to have a landlord that worries about the leaky faucet while you spend your weekends unbothered by home repairs, renting is likely better for your sanity.
Tactical Tips for Buyers
When you are 75 days out, start with a pre-qualification after an initial mortgage application. Then aim for a fully underwritten pre-approval after a complete mortgage application. Create a list of preferred neighborhoods and schedule a house-hunting trip.
By the 45-to-60-day mark, you should be making offers, finishing home inspections, and booking your movers. Expect a 30-45 day closing window and line up your utilities, school enrollments, and medical transfers early so move-in day isn’t a headache.
Choose your financing by total cost (such as upfront costs, money down, and costs and fees that might be rolled into the loan amount financed), not just the interest rate. VA Home Loans are a powerhouse for veterans and service members, offering potentially $0 down and no private mortgage insurance (PMI).
However, you will have a VA funding fee as part of the mortgage unless you have a qualifying disability rating or Purple Heart. Conventional loans can sometimes be cheaper over the life of the loan if you have strong credit and can put 20% down.
It helps to shop hard. Get same-day quotes from at least three lenders and compare the annual percentage rate (APR), whether discount points have to be paid, if lender paid credits are provided, and lock terms. A lender who understands VA nuances and PCS timelines is invaluable.
What if You Are Renting?
If you’re going the rental route, treat it like a job application. Assemble a “renter packet” with your orders, LES, solid references, and pet records. In a multi-application race, that level of organization provides credibility that could win the lease.
Always insist on a military clause for early termination due to orders. Also, budget beyond the base rent: application fees, pet fees, parking, and utility deposits add up fast. If your timeline is tight, don’t be afraid to ask for pro-rated rent or a landlord-paid deep cleaning to smooth the transition.
Funding Your Move
Even with allowances and relocation packages, cash flow pinches are inevitable. Build a dedicated “move fund” of one to two months of expenses on top of your emergency fund for PCS success. Costs like deposits, inspections, and first month’s rent often hit long before reimbursements do.
Use advances or partial reimbursements where allowed (TLA/TLE/DLA for military; relocation advances for civilians). Track every receipt and submit your vouchers immediately.
Don’t let a lack of liquidity spoil your move.
PCS success is about 80% preparation and 20% execution. Be sure to start early, choose your financing based on the total math, build a moving fund to bridge the timing gaps, and work with a relocation-savvy team. Whether you’re buying or renting, the winning move is the one that properly protects your flexibility and grows your long-term net worth.
Don’t Miss the Best of We Are The Mighty
• American troops drank 2 million energy drinks during Operation Epic Fury
• Til Valhalla: Where the phrase came from and what it means to veterans
• The inside joke names soldiers have for different unit patches
Featured

Loading comments…
Comments couldn’t be loaded. Please refresh the page.